What is your business worth today?
A written valuation and value drivers report, prepared by hand. Built by M&A advisers, exited founders and serial acquirers who combined real transaction experience with input from chartered accountants and business buyers, so the report reflects how a buyer would actually price your company.
What actually arrives
A written valuation and value drivers report, prepared for you by name
Written for your company, addressed to you by name, and set out in detail: the earnings build line by line, the range and the date it is stated as at, thirty value factors scored with the evidence, an online presence audit, the risks that would make the company hard to sell, and what to do about each one. Below is the real structure of the document, taken from the live template rather than a mock-up.
A pre-signed mutual NDA is available before you answer a single question. Ask for it at any point and it is with you the same day.
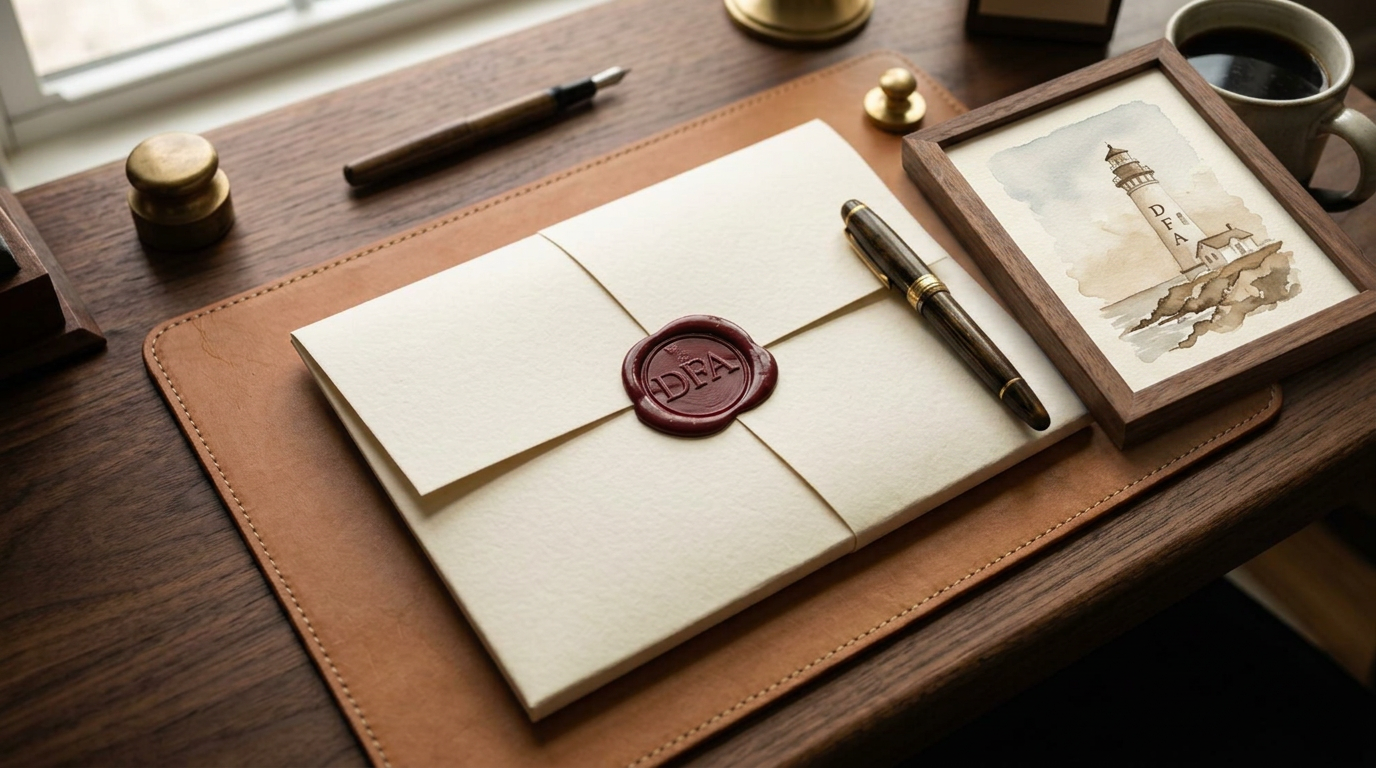
Private and confidential, prepared by hand
Dear [first name],
Thank you for the time you put into the questionnaire, and for uploading your profit and loss and balance sheet. That was not compulsory, and it has materially improved the depth and the accuracy of what follows.
Most owners we speak to are not selling for another one to three years. The purpose of this document is to give you clarity now: where the value sits, where it leaks, and what to do in the next 30 days, 90 days and twelve months to move the number.
This is a first draft. After our call we enrich it and send you a second version.
Contents
- 01Executive summaryThe range, the reasoning, and what moves it
- 02How this valuation was builtMethod, comparables, and what we excluded
- 03Earnings and adjustmentsLine by line, with add-backs accepted and rejected
- 04Valuation range and timingToday, twelve months as you are, twelve months prepared
- 05The thirty value factorsEach scored, weighted, with the evidence written out
- 06Online Visibility and DemandSearch demand, reviews, directories and social
- 07Proceeds, tax and personal wealthWhat actually reaches you on completion
- 08The improvement plan30 day, 90 day and twelve month actions
- 09What happens nextOptions, including doing nothing for two years
- 10Evidence base and sourcesEvery figure traced to where it came from
Section 06
A full online presence audit, included
We check your Google Business Profile and reviews, LinkedIn, Facebook, Trustpilot and the trade directories that matter in your sector, then measure what people actually search for and whether you appear. Buyers treat discoverability as evidence of transferable demand, so it feeds the valuation directly.
Word of mouth stays your strongest channel. A verifiable online footprint is what makes those referrals travel further and convert faster when someone checks you out.
- Google Business Profile4.7 from 128 reviews
- LinkedIn company page1,240 followers
- TrustpilotNot found on initial review
- FacebookActive, last post 4 months ago
- Organic search469 visits a month, 77 keywords
Written commentary
Illustrative figures. Your report carries your own commentary in full, with links to every profile found.
We gather everything we can before we ask you anything.
Our own connectors pull your filed accounts, your sector, your search visibility and your review profiles. You are only asked the things we genuinely cannot find, and each question is written from what we already know about your business.
Public sources only, read once, never published. Logos are shown to identify the sources we read and do not imply any endorsement or partnership.
Two documents, not one
The preliminary read answers the headline question. The in-depth report tells you what to do about the answer, which is where the money is.
Preliminary read
Around 15 pages. With you in 24 to 48 hours.
- Indicative valuation range, dated and priced on the last twelve months
- Thirty value factors scored across six dimensions
- Automated online presence audit
- Headline net proceeds illustration
Your time: about 25 to 30 minutes on the questionnaire.
In-depth valuation and value drivers report
Around 30 pages. With you in 48 to 72 hours.
- Everything in the preliminary read, re-scored with your documents and two conversations
- Risk register: what could make the company hard to sell, ranked by damage
- Mitigation plan: owner, cost and date for each risk
- Named acquirer map and proceeds modelled on your cap table
Your time: roughly 30 minutes with us, plus about 30 minutes gathering documents. Covered by a pre-signed mutual NDA before anything is shared.
The in-depth report is the one owners keep coming back to. It shows not just what the business is worth today, but where value is already leaking, what could sink a sale in diligence, and the specific 30, 90 and 365-day actions that move the number. Most owners tell us the risk register is the part they wish they had read three years earlier.
Thirty value factors, in six sections
Every factor is scored, weighted and written out with the evidence behind it. The weights below are the ones the model actually uses, and they are printed in your report.
Financials
22% weightFive factors
- Revenue growth
- Quality of earnings and accounting record
- Gross margin against the sector benchmark
- Working capital and cash conversion
- Forecast credibility and pipeline visibility
Customers and revenue
16% weightFive factors
- Customer concentration
- Contracted revenue share
- Contract quality, length and indexation
- Customer retention
- Revenue mix and cross-sell
Operations
14% weightFive factors
- Systems and sale readiness
- Service delivery and process documentation
- Accreditation and compliance scope
- Capacity to deliver the order book
- Data and reporting infrastructure
People
13% weightFive factors
- Key person dependency
- Management depth
- Workforce retention
- Documentation, training and cover
- Incentive and shareholder alignment
Strategic position
13% weightFive factors
- Market position and differentiation
- Sector acquirer appetite
- Accreditation moat
- Organic growth engine
- Exit readiness and ownership structure
Deal process and buyer access
22% weightFive factors
- Specialist representation
- Access to pre-qualified buyers
- Deal team niche expertise
- Process credibility and competitive tension
- Evidenced inbound buyer demand
We had an instant valuation calculator. We took it down, because it was wrong.
We studied the ten most widely used business valuation calculators. Nearly all of them return a figure in seconds from two or three inputs. Underneath that number sit earnings quality, customer concentration, contract cover, key person dependency, accreditations, buyer appetite and the conduct of the sale process, any one of which moves the answer by more than the whole margin of error those tools carry.
Selling your company is likely the largest transaction of your life. It deserves better than a figure produced in four seconds by a form.
What replaced it
- The career experience of M&A advisers who have run these processes, and exited founders who have sat on the other side of the table
- Our own transaction research across facilities management, building services and healthcare
- Proprietary data from thousands of acquirers who have registered with us over the last four years, telling us in their own words what they pay for and what they discount
- Thirty weighted factors, scored individually, with the evidence written out beside each score
A range you can defend in front of an acquirer is worth considerably more than a range you received quickly.
About 25 to 30 minutes, in total.
- 14 to 15 minutesThe questionnaire itself, on your phone or laptop
- 5 to 10 minutesExporting your profit and loss and balance sheet
- Nothing furtherWe take it from there and write the document
You can stop at any point and pick it up later on any device. Nothing is lost.
Both reports, at no cost, for businesses turning over more than £500,000.
We are writing these free of charge while we demonstrate what we can do. No card, no tier, no obligation to appoint us. The preliminary read costs you half an hour. The in-depth report costs you an hour, and we think it will be the most useful hour you have spent on the business this month.
Strictly confidential. Seen only by our internal team, never shown to an acquirer, and never used to train any model. If you would rather attract buyer interest quietly first, the Off-Market Register does that without naming your company.
The same business, three different numbers
Your report shows all three, with the arithmetic behind each one.
Illustrative. Preparation and a competitive process, not the calculator, create the gap.
Business owners have used this tool. Rebuilt this year with buyers, accountants and tax and wealth planners.
Comparable transaction research is refreshed every week, so the multiples reflect deals done now, not last cycle.
Listed company multiples are used as a reference and discounted for size, liquidity and owner dependence.
A specialist M&A advisory firm. 22 completed sales, and dozens more across our advisers' careers.
We work in lower-mid-market businesses, with live mandates and buyer mapping running in this space now. Your report is written by the same people who run those sales.
“I remember when we were deciding which advisors to pick, we made a great decision picking Joe from DealFlowAgent.”
Saim, Founder · sold to a US strategic acquirer


Experienced Dealmakers Lead Your Exit
A senior M&A bench, plus a sector specialist recruited for your industry on every deal.
Duncan Moore
M&A Deal Lead
Joined full-time on 22 August 2026 from the largest M&A advisory firm in the UK, owned by K3 Capital. As an ex-Director he managed teams of M&A advisors, analysts and associates, working daily with business owners, buyers and stakeholders on live acquisition deals. Selected from 260 applicants alongside colleagues from investment banking backgrounds, he brings that experience and network to lead the advisory bench across Building Services, Facilities Management, and Healthcare.
Joined full-time on 22 August 2026 from the largest M&A advisory firm in the UK, owned by K3 Capital. As an ex-Director he managed teams of M&A advisors, analysts and associates, working daily with business owners, buyers and stakeholders on live acquisition deals. Selected from 260 applicants alongside colleagues from investment banking backgrounds, he brings that experience and network to lead the advisory bench across Building Services, Facilities Management, and Healthcare.
Martin is one of the most well-connected figures in UK fire, security, building services and FM. He is Chairman of both the Fire Industry Association and the British Security Industry Association, the only person in the UK to hold both roles simultaneously. Martin spent over a decade in senior leadership at Mitie, latterly as Industry Liaison Director for its fire and security division, helping scale the business past £500m in revenue and playing a role in the £366m acquisition of Marlowe plc, which created one of the UK's largest compliance, fire and security services groups. He joined DealFlowAgent because owners in these sectors deserve a genuine sector-specialist advisor across valuation, business optimisation and buyer access. In recognition of his industry roles, he acts in a personal, non-partisan capacity.
Martin is one of the most well-connected figures in UK fire, security, building services and FM. He is Chairman of both the Fire Industry Association and the British Security Industry Association, the only person in the UK to hold both roles simultaneously. Martin spent over a decade in senior leadership at Mitie, latterly as Industry Liaison Director for its fire and security division, helping scale the business past £500m in revenue and playing a role in the £366m acquisition of Marlowe plc, which created one of the UK's largest compliance, fire and security services groups. He joined DealFlowAgent because owners in these sectors deserve a genuine sector-specialist advisor across valuation, business optimisation and buyer access. In recognition of his industry roles, he acts in a personal, non-partisan capacity.
Nick leads FM Talent Partners, the facilities management and real estate leadership search firm, and is a leading specialist in building services and FM management talent. He partners with DealFlowAgent on two-way referrals: helping business owners and acquirers fill the key roles that decide whether a business is sellable, and introducing owners who are thinking about their next chapter to a team that knows their industry and their market. Key-person dependency is one of the two most common reasons a sale collapses, and Nick fixes it at source.
Nick leads FM Talent Partners, the facilities management and real estate leadership search firm, and is a leading specialist in building services and FM management talent. He partners with DealFlowAgent on two-way referrals: helping business owners and acquirers fill the key roles that decide whether a business is sellable, and introducing owners who are thinking about their next chapter to a team that knows their industry and their market. Key-person dependency is one of the two most common reasons a sale collapses, and Nick fixes it at source.
James Duboullay
Senior M&A Advisor
- •25+ years across investment banking, M&A and fundraising
- •Sector focus: essential services and software
- •Long-standing relationships with private equity buyers and growth funds
- •Personally advising DealFlowAgent founders for the past four years
- •25+ years across investment banking, M&A and fundraising
- •Sector focus: essential services and software
- •Long-standing relationships with private equity buyers and growth funds
- •Personally advising DealFlowAgent founders for the past four years
Emerson Patton
Sector Specialist: Building Services & Facilities Management
- •20+ years advising owners in building services, fire safety, HVAC, plumbing, and construction
- •Guided 200+ companies through growth, profit improvement, and exit planning
- •Builds equity value and operational structure long before a sale
- •Partners with DFA to prepare owners for exit while the advisory team runs the sale
- •20+ years advising owners in building services, fire safety, HVAC, plumbing, and construction
- •Guided 200+ companies through growth, profit improvement, and exit planning
- •Builds equity value and operational structure long before a sale
- •Partners with DFA to prepare owners for exit while the advisory team runs the sale
Kaya Kesici
M&A Advisor, Fire Safety, Security & Compliance
- •17 completed M&A transactions over the past six years across UK SME fire safety, security and compliance-led services
- •Sell-side and buy-side experience, buyer research, acquirer mapping, outreach and live process coordination
- •Information request lists, databook prep, IC-style summaries and EV-to-equity bridge work
- •Direct sector exposure across fire protection, security systems, CCTV, access control and intruder alarms
- •17 completed M&A transactions over the past six years across UK SME fire safety, security and compliance-led services
- •Sell-side and buy-side experience, buyer research, acquirer mapping, outreach and live process coordination
- •Information request lists, databook prep, IC-style summaries and EV-to-equity bridge work
- •Direct sector exposure across fire protection, security systems, CCTV, access control and intruder alarms
Previously
Ranger Fire & Security · Complete Building Services · Compliance Group
- •22 completed M&A transactions
- •Direct relationships with hundreds of strategic and financial acquirers
- •Previously built a mobility and field services business to 30 staff and 6 UK warehouses, then sold via competitive process with an EY M&A partner
- •Raised £2m in funding; placed 3rd of 1,900 at OnStage (the "Y Combinator of Europe")
- •Full-stack developer of advanced agent systems and second-brain tooling for the M&A process
- •22 completed M&A transactions
- •Direct relationships with hundreds of strategic and financial acquirers
- •Previously built a mobility and field services business to 30 staff and 6 UK warehouses, then sold via competitive process with an EY M&A partner
- •Raised £2m in funding; placed 3rd of 1,900 at OnStage (the "Y Combinator of Europe")
- •Full-stack developer of advanced agent systems and second-brain tooling for the M&A process
Sector Expert
Industry-Specific Advisor
For every engagement we add a sector specialist from your industry to the core team: a 15–25 year operator or advisor with direct relationships in your niche. Recruited per deal so you get the right fit, not a generalist.
For every engagement we add a sector specialist from your industry to the core team: a 15–25 year operator or advisor with direct relationships in your niche. Recruited per deal so you get the right fit, not a generalist.
The bench is growing. Two senior M&A hires confirmed for late July 2026, selected from 200+ applicants out of Goldman Sachs, Deutsche Bank, EY, KPMG and leading boutique M&A firms. See open roles →
The AI layer behind every advisor
Two in-house AI systems work alongside the human bench. They are software, not people, built and supervised by the advisory team.
Sage
AI Deal Concierge
Available 24/7. Monitors every signal in your deal and keeps the advisory team one step ahead. Trained on thousands of M&A transactions.
Sterling
Buy-Side Deal Origination Agent
Engages 13,000+ acquirers to surface live mandates and intent, then feeds your advisors with warm, ranked buyer matches.
Read the full methodology
How this valuation is actually calculated
This is not a multiple pulled from a table. The engine combines the career experience of our M&A advisers and exited founders with research into completed transactions across facilities management, building services and healthcare, and it is designed to survive scrutiny from the people who will eventually examine your business: financial, commercial and operational due diligence.
Step one. Fix the earnings base
We start with your 2026 full-year revenue and pre-tax profit, then work through the add-backs a buyer would genuinely accept: owner remuneration above market rate, one-off legal or recruitment costs, non-trading assets, and related-party charges. Anything we cannot evidence is left out, because a due diligence team will strip it out later anyway.
Step two. Choose the right earnings measure
Owner-operated businesses are valued on Seller Discretionary Earnings. Businesses with a management team below the owner are valued on adjusted EBITDA. We show both where the business sits between the two, so the basis of the number is never ambiguous.
Step three. Apply a transaction multiple, not a rule of thumb
The multiple comes from completed transactions in your specific niche, not a sector average. It is then adjusted across more than thirty weighted factors covering finance quality, contract and revenue durability, customer concentration, people and key-person risk, operations and systems, accreditations, and market position.
Step four. Show the arithmetic
Every report sets out the earnings build line by line, the multiple applied, the factors that pushed it up or down, and the resulting range. It is written so a chartered accountant, a financial due diligence lead or a serial acquirer can follow the logic and challenge it. If a number cannot be defended, it does not appear.
Three timings, three different numbers
A valuation is meaningless without a date attached to it. Your report sets out what the business is worth on each of the following bases, using your 2026 full-year figures as the anchor.
Completion around December 2026 or January 2027
Based on your 2026 numbers as they stand, with the business presented as it is today. This is the honest starting point and the figure most owners have never actually seen.
Completion at the end of 2027
Twelve more months of trading with the same systems, the same customer mix and the same dependence on the owner. The value moves with your earnings and with the sector multiple. It rarely moves much on its own.
Completion at the end of 2027, after the work
The same twelve months, used properly: contracted revenue increased, reporting cleaned up, customer concentration reduced, the owner taken out of daily delivery, systems documented. On the businesses we work with this typically supports a valuation 10 to 50 per cent higher than the do-nothing case.
What a properly run process adds on top
The scenarios above assume a competent sale. They are not the ceiling. Price is set by competitive tension, and tension is manufactured by the process, not by the business. Owners who take the first approach that lands in their inbox routinely sell at a fraction of what the same company would fetch against a mapped field of strategic and financial buyers.
A specialist sell-side process typically moves the final consideration 10 to 100 per cent above an unadvised bilateral deal, and we have doubled the number on the table on real mandates. Structure matters as much as headline price: the split between cash at completion, deferred consideration, earn-out and equity roll-over is where most value is quietly lost.
This exercise produces indicative analysis to help you plan. It is not financial, tax, investment or legal advice, and it is not a formal valuation opinion. Anything touching share proceeds, tax or structuring should be taken to a qualified adviser before you act on it.
Explore our sector valuation guides:
HVAC & Heating·Electrical Contractors·Fire Safety·Security Systems·Compliance, Testing & Inspection·Commercial Plumbing & Drainage·Waste Management & Recycling·Pest Control·Dental Practices·Care Homes·Heat Pumps·Maintenance Contracts·All valuation guides
Related: Exit readiness hub·Essential services M&A·Compare advisory routes